What Is the IRS?
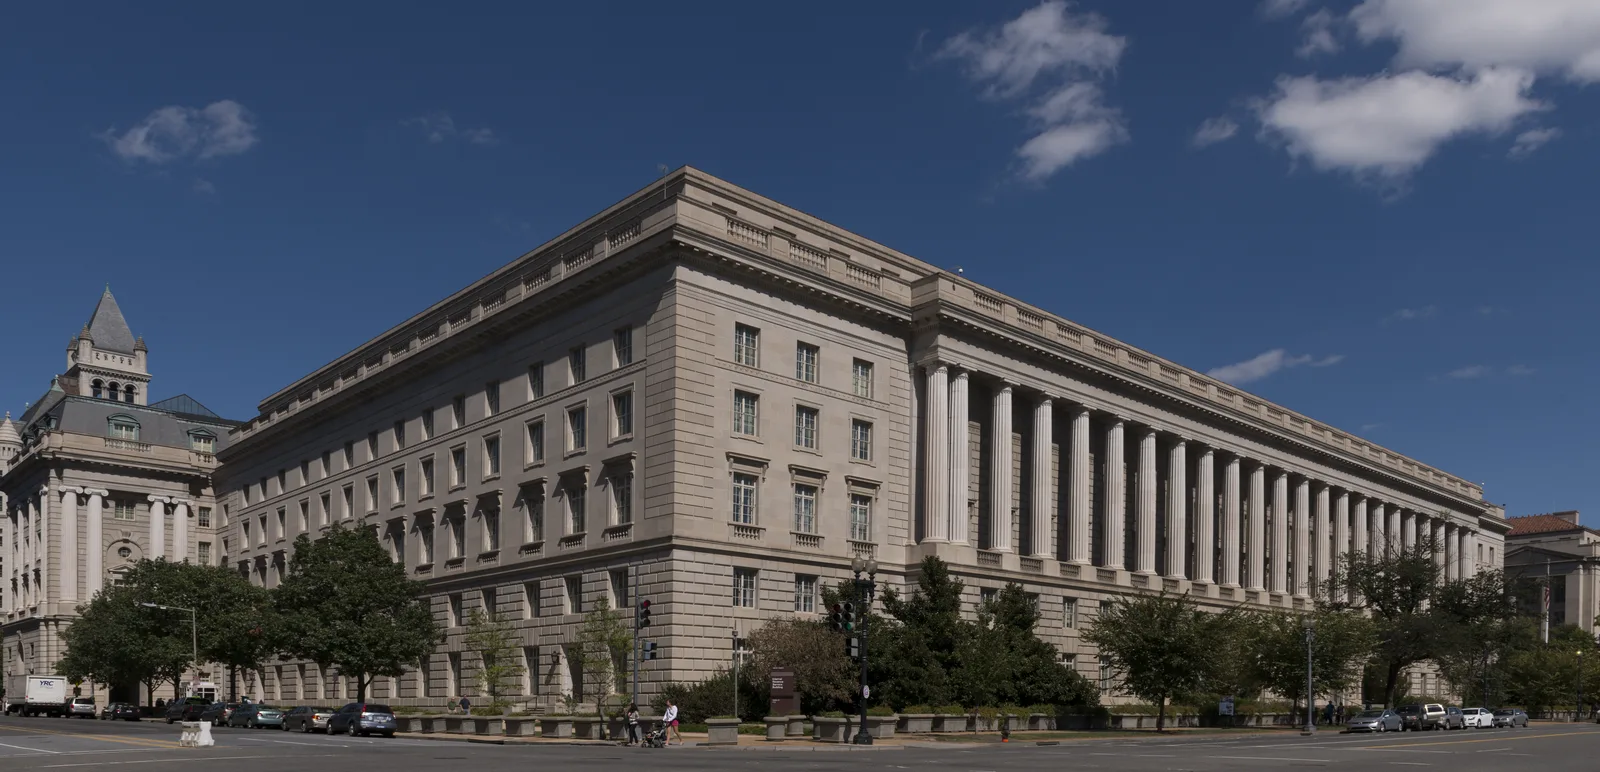
The Internal Revenue Service is the bureau within the Treasury Department responsible for collecting nearly all federal tax revenue, more than $5 trillion in a typical year, and administering the tax code Congress writes. It processes over 160 million individual returns annually, issues most federal tax refunds, and enforces compliance through audits and, in the most serious cases, criminal investigation.
Who's Running the IRS Right Now?
As of this page's publication, the IRS does not have a Senate-confirmed Commissioner. Danny Werfel departed in January 2025, followed by a rapid succession of acting leaders; Billy Long was confirmed in June 2025 but left the role weeks later that August. Treasury Secretary Scott Bessent served as Acting Commissioner into 2026 before his temporary legal authority expired, and day-to-day leadership has since fallen to an appointed "IRS CEO" role, an arrangement legal commentators have flagged as constitutionally unusual since it exercises commissioner-level authority without Senate confirmation. This is covered in more detail in the History tab.
How the IRS Is Organized
This division serves individual taxpayers who earn income primarily through wages and investments, roughly the majority of all individual filers in the country. It processes most individual returns, issues most refunds, and runs the IRS's taxpayer-facing phone lines and walk-in Taxpayer Assistance Centers.
Wage and Investment also administers the agency's Volunteer Income Tax Assistance (VITA) program, which coordinates IRS-trained community volunteers to prepare free returns for low- and moderate-income filers, people with disabilities, and taxpayers with limited English proficiency.
It handles the largest volume of work at the IRS by far, more than 160 million individual returns a year, most of them electronic. Because wage and investment income is reported to the IRS separately by employers and banks on W-2 and 1099 forms, the agency can match those forms against a return automatically, which is why this population has the highest voluntary compliance rate and the lowest audit rate.
The division's service performance is the number the National Taxpayer Advocate tracks most closely. In the worst pandemic-era years the IRS answered well under a fifth of the calls to its main phone lines; after the 2022 funding increase it hired thousands of phone and walk-in staff and pushed the answer rate and wait times back to more normal levels before the 2025 staffing cuts.
This division handles roughly 57 million small businesses and self-employed taxpayers, including sole proprietors, partnerships, and S corporations with assets under $10 million. It is also home to most of the IRS's field examination (audit) staff who handle in-person audits of these filers.
Because small-business and self-employment income is harder for the IRS to verify against third-party reporting than a W-2 wage, this division's compliance work focuses heavily on areas prone to underreporting, such as cash-heavy businesses and mixed personal and business expenses.
The IRS estimates that sole proprietors and other self-employed people report only about 45 percent of the income they actually earn, compared with roughly 99 percent for wages, and this gap is the single largest component of the roughly $600 billion-plus annual "tax gap" between taxes owed and taxes paid on time.
The division also administers employment (payroll) taxes, the excise taxes on fuel, alcohol, tobacco, and other goods, and the estate and gift tax. Its collection staff handle liens, levies, wage garnishments, and installment agreements for taxpayers who owe but have not paid.
LB&I oversees corporations, partnerships, and S corporations with assets over $10 million, along with the international tax issues that affect multinational corporations and high-income individuals with foreign assets. Its examinations of the largest corporate filers are typically the most complex and longest-running audits the IRS conducts.
LB&I also enforces the Foreign Account Tax Compliance Act (FATCA), which requires foreign financial institutions to report accounts held by U.S. taxpayers, one of the IRS's primary tools for detecting offshore tax evasion.
The biggest corporations are audited nearly every year as a matter of course; the audit is continuous rather than triggered by a red flag. Large corporate audits routinely take three to five years and often end in the IRS's independent Appeals office or in U.S. Tax Court over technical questions worth tens or hundreds of millions of dollars.
Much of LB&I's work is "transfer pricing," checking whether a multinational shifted profits to low-tax countries by the prices its own subsidiaries charged each other. It also implements the 2017 tax law's international provisions and the 15 percent corporate alternative minimum tax and the global minimum-tax framework negotiated at the OECD in the 2020s.
TE/GE oversees the tax-exempt sector, including the roughly 1.8 million charities, churches, and other nonprofit organizations recognized under Section 501(c)(3) of the tax code, along with employee retirement plans, and state and local governments.
This is the division at the center of the 2013 targeting controversy, when its exempt-organizations unit was found to have improperly singled out conservative nonprofit applicants for extra scrutiny during the application process for tax-exempt status.
Tax-exempt organizations account for a large share of the U.S. economy, roughly 10 percent of private employment and trillions of dollars in assets, and they file public information returns (the Form 990 series) that anyone can read, making the sector unusually transparent compared with private businesses.
The division also polices the line between permitted and prohibited activity: 501(c)(3) charities may not intervene in political campaigns and face limits on lobbying, while 501(c)(4) "social welfare" groups may do some political spending without disclosing donors, a distinction at the heart of the "dark money" debate. It reviews retirement plans for compliance with the tax rules that make 401(k) and pension contributions tax-favored.
IRS-CI is the only federal law enforcement agency with jurisdiction over federal tax crimes, and its roughly 2,000 special agents investigate everything from individual tax evasion to complex financial crimes including money laundering, cryptocurrency fraud, and public corruption.
IRS-CI maintains a conviction rate above 90%, among the highest of any federal law enforcement agency, largely because its agents build cases around documentary financial evidence, bank records, and forensic accounting rather than eyewitness testimony.
IRS-CI traces to 1919, when a small unit of postal inspectors was borrowed to investigate tax fraud, and it is best known historically for the tax-evasion conviction that sent Al Capone to prison in 1931 after other charges failed. Its agents are the federal government's specialists at "following the money."
The division leads or co-leads major task forces on narcotics money laundering, terrorist financing, and, more recently, pandemic-relief and identity-theft fraud, and it runs the government's main capability for tracing cryptocurrency transactions, work that has recovered billions of dollars in stolen or laundered digital assets.
From a Civil War Tax to the Modern IRS
The agency that would become the IRS was created to fund the Civil War and did not become a permanent fixture of American life until the 16th Amendment in 1913. Its history since then is a story of steady growth in responsibility punctuated by periodic scandal, reform, and, most recently, an unusually turbulent stretch of leadership churn and budget fights.
To help finance the Civil War, Congress passed the nation's first federal income tax in the Revenue Act of 1861, a flat 3% tax on incomes over $800 that was never effectively collected, and President Lincoln then signed the Revenue Act of 1862, which created the Commissioner of Internal Revenue and replaced it with graduated rates of 3% and 5%. Congress allowed the wartime income tax to expire in 1872, and for the following four decades the federal government relied primarily on tariffs and excise taxes for revenue.
The same year, the Legal Tender Act authorized the paper currency known as 'greenbacks,' and a Treasury operation set up to trim and seal the new notes grew into the Bureau of Engraving and Printing; the greenbacks helped finance the Union war effort when the government's gold and silver reserves ran short.
The 1862 law also imposed a web of excise taxes, on liquor, tobacco, playing cards, gunpowder, feathers, telegrams, legal documents, and much more, and created the licensing system for alcohol and tobacco that the bureau enforced for the rest of the 19th century. By 1866 the wartime income tax alone brought in the equivalent of hundreds of millions of dollars.
An 1894 attempt to bring back a peacetime income tax was struck down by the Supreme Court in Pollock v. Farmers' Loan & Trust Co. (1895), which held that a tax on income from property was a "direct tax" that the Constitution required to be apportioned among the states by population. That ruling is what made a constitutional amendment necessary.
Ratified in February 1913, the 16th Amendment gave Congress the constitutional authority to levy an income tax directly on individuals without apportioning it among the states by population, overturning an 1895 Supreme Court decision that had struck down an earlier federal income tax law as unconstitutional.
The first permanent federal income tax under the new amendment applied only to the wealthiest Americans, with a top rate of 7% on incomes over $500,000 (roughly $16 million in today's dollars), a far narrower tax base than the income tax most Americans are familiar with today.
Fewer than 1 percent of households owed any income tax in 1913, and the original Form 1040 was three pages plus a page of instructions. The tax stayed a "class tax" on the rich until World War II, when Congress lowered the exemptions and raised rates to turn it into a "mass tax" paid by most working Americans; the number of taxable individual returns jumped from about 4 million in 1939 to over 40 million by 1945 (total returns filed rose from about 7.6 million to about 50 million).
The amendment was proposed by a Republican Congress in 1909 partly as a political maneuver, on the assumption that conservative state legislatures would never ratify it. Instead it was ratified by 42 states within four years, driven by Progressive-era anger at reliance on tariffs that fell hardest on consumers.
The Current Tax Payment Act of 1943 introduced payroll withholding, requiring employers to withhold estimated income tax directly from workers' paychecks and remit it to the government, rather than taxpayers paying their full annual bill in one lump sum. The change was designed to fund the rapidly expanding cost of World War II with a steady stream of revenue.
Withholding fundamentally changed how most Americans experience the income tax, since most wage earners now pay throughout the year via their employer rather than as a single, highly visible payment, a design economists have long noted makes the tax less politically salient than a lump-sum bill would be.
To ease the switch, Congress largely forgave one year of tax liability so that people were not paying both the old lump sum and the new withholding at once, a compromise associated with the Macy's executive and economist Beardsley Ruml. Withholding is why most filers now get a refund: their employer typically withholds slightly more than they owe.
Withholding made mass tax collection administratively possible, but it also shifted much of the compliance burden onto employers, who now compute, withhold, deposit, and report payroll and income taxes for their workers. Payroll taxes withheld and remitted by employers are today the single largest source of federal revenue.
In 1953, President Eisenhower reorganized the Bureau of Internal Revenue and renamed it the Internal Revenue Service, part of a broader modernization effort intended to professionalize tax administration and move away from the patronage-based appointment system that had periodically produced corruption scandals in the bureau's earlier decades.
The reorganization shifted the agency toward the more decentralized, function-based structure, organized around taxpayer types rather than geography, that with further modernization in the late 1990s still largely shapes how the IRS operates today.
The change followed a 1951-52 scandal in which a House subcommittee found bribery, extortion, and favoritism across dozens of the bureau's regional collector offices; more than 100 employees were fired or resigned and several were convicted. Replacing politically appointed "collectors" with career civil-service district directors was the central fix.
The 1950s and 1960s also brought the IRS's first computers. The agency assigned every taxpayer a Social Security-based account number, built a national computer center in Martinsburg, West Virginia, and by 1967 was processing all returns through a central master file, the backbone system, since heavily patched, that the agency was still trying to fully replace decades later.
Following 1997 and 1998 congressional hearings in which taxpayers described aggressive and sometimes abusive IRS collection tactics, Congress passed the IRS Restructuring and Reform Act of 1998, the most significant overhaul of the agency's structure and taxpayer protections since 1953.
The law created the modern Taxpayer Advocate Service, shifted the burden of proof to the IRS in certain civil tax disputes, and reorganized the agency around the four operating divisions serving different types of taxpayers that still exist today, replacing the old geography-based district office system.
It also created a nine-member IRS Oversight Board of mostly private citizens, set a fixed five-year term for the commissioner, added "innocent spouse" relief for people whose partner underreported income, and required the IRS to tell taxpayers their rights before enforcement action. Some of the dramatic hearing testimony about IRS abuses was later found by government investigators to have been exaggerated or unverifiable.
The 1998 law's restrictions on enforcement, combined with flat budgets, coincided with a steep drop in audits and collections over the following years; by the mid-2000s the individual audit rate had fallen well below 1 percent, and it kept declining as the agency's budget shrank in real terms through the 2010s.
The 2010 Affordable Care Act gave the IRS new responsibilities enforcing the law's individual mandate (a tax penalty for not carrying health insurance, later reduced to $0 by Congress in 2017) and administering premium tax credits for people who bought insurance through the ACA marketplaces.
The added workload made the IRS a focal point of the broader political fight over the ACA, and Congress subsequently cut the agency's budget in real terms for several consecutive years even as its responsibilities grew, a period the agency's own National Taxpayer Advocate later cited as a major driver of declining service quality.
The advance premium tax credit alone requires the IRS to reconcile, on tens of millions of returns each year, the subsidy a household received during the year against the subsidy its actual income entitled it to, a calculation that is a common source of filing errors and delayed refunds.
Between 2010 and 2021 the IRS budget fell by roughly 20 percent after inflation while the number of returns rose, its workforce dropped by about 20 percent, and enforcement staff by nearly 40 percent. The Supreme Court's Sebelius (2012) decision upheld the individual mandate specifically as a tax within Congress's power, which is why the IRS rather than a health agency enforced it.
In May 2013, a Treasury Inspector General for Tax Administration report confirmed that IRS staff in the Tax Exempt and Government Entities division had improperly used terms like 'tea party' and 'patriot' to flag applications from conservative nonprofit groups for extra scrutiny when they applied for tax-exempt status. Lois Lerner, who headed the exempt-organizations unit, invoked her Fifth Amendment right before Congress and resigned later that year.
The Department of Justice settled two consolidated lawsuits brought by more than 450 affected groups for a combined $3.5 million, with a federal judge granting final approval in August 2018. In approving the settlement, the Justice Department under the incoming administration publicly stated that Lerner had failed to stop the targeting and had concealed it from Congress for roughly two years, a conclusion that reversed an earlier 2015 Justice Department finding.
The context was a surge in applications after the Supreme Court's 2010 Citizens United decision, which prompted many new 501(c)(4) "social welfare" groups seeking to do political spending without disclosing donors. A swamped Cincinnati screening unit used keyword shortcuts to sort them; a later, broader Inspector General review found progressive-leaning terms such as "progressive" and "occupy" had also been used on some watch lists.
No evidence was found that anyone outside the IRS directed the practice, and no criminal charges were brought. The episode led to the resignation of the acting commissioner, years of congressional hearings, a failed 2014 House effort to impeach Commissioner John Koskinen, and lasting bipartisan distrust that shaped later fights over IRS funding.
The 2022 Inflation Reduction Act allocated approximately $79.4 billion in supplemental IRS funding over ten years, the largest single funding increase in the agency's history, intended to modernize outdated technology, improve customer service, and expand enforcement focused on large corporations and high-income individuals rather than average filers.
The funding proved politically contentious almost immediately. Congress clawed back portions of it in subsequent legislation, including $1.4 billion under the 2023 Fiscal Responsibility Act and further reductions in later appropriations bills, and government watchdog reports through 2025 tracked the shrinking, disputed remainder of the original allocation.
About $46 billion of the original total was for enforcement, $25 billion for operations, $4.8 billion for technology modernization, and $3.2 billion for taxpayer services. The Treasury pledged that audit rates for households earning under $400,000 would not rise above historical levels, a commitment critics said was hard to verify.
The Congressional Budget Office estimated the enforcement money would raise more revenue than it cost, on the order of $180 billion over a decade before the clawbacks, because audits of high-income filers and large partnerships recover multiples of what they cost. Supporters framed the money as closing the tax gap; opponents framed it as a threat of aggressive enforcement, and the dispute became a recurring feature of budget negotiations.
Using a portion of the Inflation Reduction Act funding, the IRS launched Direct File in the 2024 filing season, a free government-run electronic filing system that let eligible taxpayers in 12 pilot states file simple federal returns directly with the IRS at no cost, without using a commercial tax preparation company. The program expanded to 25 states for the 2025 filing season.
Direct File was itself the product of a study Congress ordered as part of the Inflation Reduction Act, and its design deliberately avoided routing taxpayers through commercial software, a structure that drew both praise from consumer advocates and sustained opposition from commercial tax preparation companies.
The pilot was limited to straightforward situations, W-2 wages, Social Security, interest, the standard deduction, and a handful of credits, and users then had to file their state return separately through a state site. The IRS reported high satisfaction scores among the roughly 140,000 people who used it in 2024, and about 30 nations already offer some form of government-run or pre-filled return.
The United States is unusual among wealthy countries in relying so heavily on commercial preparation: most Americans pay a preparer or buy software, and the industry, led by Intuit and H&R Block, has lobbied for two decades against a free government option, including through the Free File Alliance, a public-private program whose participation and reach had shrunk over the years.
2025 was one of the most turbulent years in the modern IRS's administrative history. Commissioner Danny Werfel departed in January 2025, followed by a rapid succession of acting leaders, workforce reductions of roughly 27,000 employees (about a quarter of the agency's staff) through layoffs and deferred resignation offers, and, in the fall of 2025, Treasury's decision to shut down the Direct File program entirely, citing low taxpayer uptake, below half of one percent of eligible federal returns, and its per-return cost.
Billy Long was confirmed as IRS Commissioner in June 2025 but departed the role just weeks later in August 2025. As of this page's publication, no Senate-confirmed Commissioner has since been seated; Treasury Secretary Scott Bessent served as Acting Commissioner into 2026 before his temporary authority expired, and day-to-day leadership has since fallen to an appointed 'IRS CEO' role, an arrangement legal commentators have flagged as constitutionally unusual since it functions as commissioner-level authority without Senate confirmation.
The cuts fell heavily on the enforcement and technology staff the 2022 funding had hired; the Treasury Inspector General reported that the agency lost a large share of its revenue agents and IT specialists in a matter of months. The National Taxpayer Advocate warned that combining a smaller workforce with an unfinished technology overhaul risked a return to the long phone waits and refund delays of the pandemic years.
The year also saw disputes over data: an agreement to share taxpayer data with immigration enforcement prompted the resignation of several senior IRS officials and a lawsuit, and a separate controversy involved access to IRS systems by outside teams reviewing agency operations. Tax-law scholars noted that the "IRS CEO" title has no basis in the Internal Revenue Code, which vests the agency's authority in a Senate-confirmed Commissioner.
From Paycheck to Refund
Most Americans' relationship with the IRS runs through withholding from a paycheck, an annual return, and, for most filers, a refund. Here's how each piece of that system actually works, including what changed when the IRS shut down its Direct File program in 2025.
The federal income tax is progressive, meaning it applies a series of increasing rates to different slices, or 'brackets,' of income rather than one flat rate on all of it. As of 2026 there are seven brackets, ranging from 10% to 37%, and moving into a higher bracket only raises the rate on the income within that bracket, not on all of a filer's income.
This is one of the most commonly misunderstood parts of the tax code: a taxpayer whose top dollar is taxed at 24% does not pay 24% on their entire income, only on the portion that falls within the 24% bracket. Everything below that is still taxed at the lower rates that applied to those earlier brackets.
The rate that matters for most decisions is the "effective" rate, total tax divided by total income, which is always lower than the top bracket. A married couple with $120,000 of taxable income in 2026 is in the 22 percent bracket but pays an effective federal income-tax rate closer to 13 percent once the lower brackets and the standard deduction are counted.
The bracket thresholds, the standard deduction, and dozens of other figures are adjusted for inflation each year, which is why paychecks and withholding tables change every January. Capital gains and qualified dividends are taxed on a separate, lower rate schedule (0, 15, or 20 percent), one reason very high earners can have a lower effective rate than some middle-income wage earners.
Most employees have income tax withheld from every paycheck based on the information they provide their employer on Form W-4, an estimate of their expected tax liability for the year. Employers remit that withheld money to the IRS on the employee's behalf throughout the year rather than the employee paying a lump sum at filing time.
Because withholding is only an estimate, most filers either overpay slightly, resulting in a refund, or underpay slightly, resulting in a balance due when they file. Significant life changes, a new job, marriage, or a new dependent, are the most common reasons a taxpayer's withholding ends up mismatched with what they actually owe.
The W-4 was redesigned in 2020 to drop the old system of "allowances" in favor of dollar figures for dependents, other income, and extra withholding, a change meant to make it more accurate but which many filers found confusing. The IRS offers a "Tax Withholding Estimator" tool to help people set it.
People with income that is not subject to withholding, self-employment, investment gains, rental income, retirees living on portfolio withdrawals, generally must make quarterly "estimated tax" payments instead, and can owe an underpayment penalty if they wait until April. Roughly three-quarters of filers receive a refund each year, averaging around $3,000.
The large majority of individual returns are now filed electronically, either through commercial tax software, a paid preparer, or the IRS Free File program, a public-private partnership with commercial tax software companies that offers free federal filing to taxpayers under an income threshold.
Direct File, the IRS's own free government-run e-filing system launched in 2024 and expanded to 25 states in 2025, was shut down by Treasury in the fall of 2025 and is not available for the 2026 filing season. Officials cited its low usage rate, under half of one percent of eligible federal returns, and its cost of roughly $138 per return filed; the program's supporters had argued it offered a genuinely free alternative to commercial software. Congress separately allocated funding for Treasury to study other free-filing options going forward.
About 90 percent of individual returns are now e-filed, up from under 20 percent in 2000; the IRS pushed the shift with faster refunds and, since 2011, a rule requiring most paid preparers to e-file. Roughly 60 percent of filers use a paid preparer and most of the rest use software, so only a small minority still fill out paper forms by hand.
Free File, the older program, is available to filers under an income cap (about $84,000 in recent years) but is used by only a few percent of eligible taxpayers, partly because participating companies were found to have hidden their free products from search engines and steered users to paid versions, conduct that led to a 2022 multistate settlement with Intuit. The IRS also offers its own no-frills "Free File Fillable Forms" for any income level.
The IRS issues more than $300 billion in individual refunds each year, and most electronically filed refunds are issued within about 21 days when a return has no errors and is not selected for additional review. Paper returns and returns requiring manual review take substantially longer.
Some of the largest refunds flow from refundable tax credits like the Earned Income Tax Credit and the Child Tax Credit, which can reduce a filer's tax bill below zero and pay out the difference as cash, functioning as one of the federal government's largest anti-poverty programs even though it is administered entirely through the tax code rather than a traditional benefits agency.
By law the IRS cannot release any refund that includes the EITC or the additional Child Tax Credit before mid-February, an anti-fraud delay Congress added in 2015 so the agency has time to match returns against employer W-2 forms. For many low-income households the refund is the single largest cash sum they receive all year, and it heavily funds tax-preparation businesses that market refund-anticipation products.
Refund fraud through stolen identities was a large problem in the early 2010s, when criminals filed fake returns using real Social Security numbers before the true taxpayer filed; the IRS cut it sharply with W-2 verification, filing-pattern filters, and an optional "Identity Protection PIN" that any taxpayer can request. The agency still holds millions of returns each year for identity or accuracy review, which delays those refunds by weeks or months.
Audits, Investigations, and Taxpayer Protections
Audit rates are far lower, and far more concentrated by income level, than most people assume. Here's what the IRS's own data shows about who actually gets audited, how the agency's criminal investigators work, and the rights every taxpayer has when dealing with the IRS.
According to the IRS's own 2024 Data Book, the overall individual audit rate is roughly 0.5%, about 1 in every 200 returns filed. Audit rates are not evenly distributed across income levels: filers reporting no income were audited at about 0.3%, those earning $25,000 to $50,000 at about 0.2%, and most middle-income filers between $50,000 and $500,000 at roughly 0.1%, the lowest rates of any income band.
Audit rates rise again at the top of the income scale, reaching about 0.6% for filers earning $500,000 to $1 million and 1.1% for those earning $1 million to $5 million. The IRS closed more than 505,000 audits in 2024, recommending over $29 billion in additional tax. These figures predate the significant 2025 staffing reductions, so they do not yet reflect what effect, if any, the smaller workforce has had on audit coverage.
The great majority of audits are "correspondence audits" conducted entirely by mail over a single issue, often a missing 1099 or a questioned credit, rather than the in-person "field audit" most people picture. EITC claimants have long been audited at a rate several times the overall average, because the credit's eligibility rules (residency of a child, relationship, income) are error-prone and the audits are cheap to run by mail, a pattern the National Taxpayer Advocate has repeatedly criticized as regressive.
The IRS also runs an automated "underreporter" program that matches every return against the W-2s and 1099s third parties file and sends millions of notices a year proposing additional tax; these are not counted as audits. Studies by IRS and academic economists estimate that each additional dollar spent auditing the top 1 percent of earners returns roughly $5 to $12 in recovered tax, far more than audits lower down.
IRS Criminal Investigation is the only federal law enforcement agency with jurisdiction to investigate potential criminal violations of the tax code, and its roughly 2,000 special agents also investigate financial crimes that intersect with tax law, including money laundering, public corruption, and cryptocurrency-based fraud.
IRS-CI maintains one of the highest conviction rates of any federal law enforcement agency, consistently above 90%, a track record the agency attributes to building cases on documentary and forensic financial evidence such as bank records and transaction histories, rather than relying primarily on witness testimony.
Criminal tax cases are relatively few, a few thousand investigations and roughly 1,500 to 2,500 convictions a year, because the government must prove willful intent beyond a reasonable doubt, a much higher bar than the civil fraud penalty. Prison sentences average around three years, and a criminal conviction does not erase the civil tax debt, which the IRS still collects.
IRS-CI's forensic and cryptocurrency-tracing skills have made it a partner on cases well beyond tax: it helped take down the Silk Road darknet market, traced ransom payments in ransomware cases, and worked the finances behind terrorism, human-trafficking, and large public-corruption prosecutions. Its agents are the ones who "follow the money" in multi-agency task forces.
Adopted by the IRS in 2014, the Taxpayer Bill of Rights groups existing taxpayer protections scattered throughout the tax code into ten clearly stated rights, including the right to be informed, the right to quality service, the right to pay no more than the correct amount of tax, and the right to appeal an IRS decision in an independent forum.
The Taxpayer Bill of Rights does not create new legal protections beyond what already existed in the tax code, but it does require the IRS to display and explain these rights prominently, part of a broader push, led by the National Taxpayer Advocate's office, to make the agency's existing obligations to taxpayers easier to understand and invoke.
Congress wrote the ten rights into law in 2015. They also include the right to privacy, the right to confidentiality, the right to retain representation (an accountant, enrolled agent, or attorney), and the right to a "fair and just tax system," which the Advocate uses to press the IRS to weigh a taxpayer's circumstances.
Practical protections behind the rights include the ability to take a dispute to the IRS's independent Office of Appeals before paying, to petition the U.S. Tax Court without paying first, to request an "offer in compromise" or hardship status when collection would be unfair, and to have penalties abated for reasonable cause or a first-time mistake.
The Taxpayer Advocate Service is an independent office within the IRS, created by the 1998 Restructuring and Reform Act, that helps taxpayers resolve problems they haven't been able to fix through normal IRS channels, particularly cases involving financial hardship or significant delays.
The office is led by the National Taxpayer Advocate, who reports directly to Congress twice a year, independent of IRS management, on the agency's most serious problems and recommendations for fixing them, giving the office a degree of institutional independence unusual for a unit operating inside the agency it oversees.
It has a local office in every state plus overseas coverage and handles a couple hundred thousand cases a year, and it can issue a "Taxpayer Assistance Order" directing the IRS to act or stop acting when a taxpayer faces significant hardship. Its two required annual reports, the Annual Report to Congress and the Objectives Report, are among the most detailed public accounts of how the tax system is actually working.
The Advocate has been a persistent internal critic on issues such as poor phone service, the backlog of unprocessed paper returns after the pandemic, the high audit rate on low-income EITC filers, delays in identity-theft cases, and the risk that the 2025 staffing cuts would undo the service gains of the prior three years. Congress often turns the office's recommendations into legislation, including much of the 2019 Taxpayer First Act.
Six Facts Worth Knowing
A quick-reference set of facts drawn from the sourced material throughout this page.
The federal income tax was only ruled constitutionally permanent in 1913 with the 16th Amendment, decades after the Treasury Department itself was created in 1789.
As of 2026, the IRS has gone without a Senate-confirmed Commissioner for an extended stretch, an unusually unsettled leadership situation even by the standards of a role that has seen frequent turnover in recent years.
The IRS's Direct File program, a free government-run e-filing system, was shut down by Treasury in late 2025 after roughly two filing seasons and is not available for 2026, ending a program that had expanded to 25 states.
IRS Criminal Investigation maintains a conviction rate above 90 percent, among the highest of any federal law enforcement agency, built almost entirely on documentary financial evidence.
The IRS workforce shrank by roughly a quarter in 2025 alone, through layoffs and deferred resignation offers, one of the largest single-year staffing reductions in the agency's modern history.
Middle-income filers are audited at some of the lowest rates of any income group, while audit rates rise again for filers earning more than $500,000 a year, according to the IRS's own 2024 Data Book.
Sources & Further Reading
- IRS, About IRS
- IRS 2024 Data Book
- Treasury Inspector General for Tax Administration (TIGTA)
- IRS Taxpayer Bill of Rights
- Taxpayer Advocate Service
- Congressional Research Service
- GAO, IRS Tax Filing Oversight
Staffing, funding, and leadership figures reflect reporting available as of this page's publication in August 2026. The exact remaining balance of the Inflation Reduction Act's original IRS funding allocation is disputed across sources due to overlapping rescissions in subsequent legislation, and is described here in general terms rather than as a single precise figure. Audit statistics are sourced to the IRS's 2024 Data Book and predate the agency's 2025 workforce reductions.